
Backtesting & Statistics
10 articles
How to validate a strategy with data instead of faith: what a correct backtest is, hindsight bias, the metrics that matter (win rate, risk-reward, profit factor, max drawdown), and how to log your trades to know whether your edge is real.

What is backtesting and how do you validate a strategy with data?
Backtesting is testing your strategy against historical data before you risk real money. What is it? The hindsight bias that ruins home-made backtests, and how to do it honestly.

Which metrics actually matter when evaluating a strategy?
Win rate, risk-reward, profit factor and max drawdown: the four figures that define a strategy. And why is win rate alone the most misleading of them all?

Expectancy, Sharpe and Sortino: the metrics beyond win rate
Win rate tells you how often you are right, not whether you make money. Expectancy answers whether the edge exists; Sharpe and Sortino tell you what it cost to collect it.

What is forward testing and why isn't a backtest enough?
A backtest tells you how your strategy behaved in the past; forward testing tells you if it works when you don’t know the future. Demo vs live, what it reveals and how long to run it.

How do you log your trades to know whether your strategy works?
Every metric of a strategy comes from your data. What to record on each trade, why log in R, and how to turn the record into decisions that improve your trading.
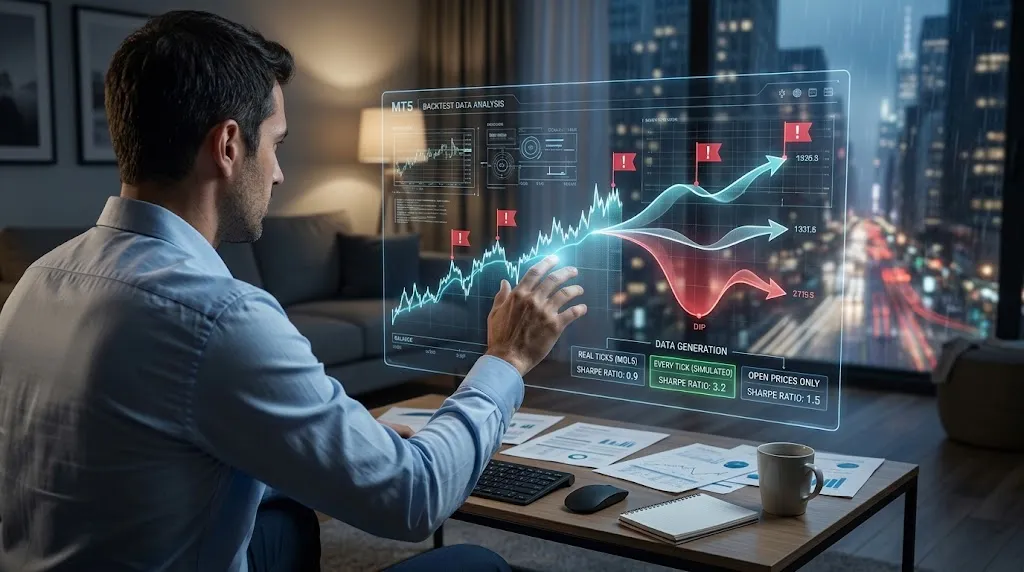
What does the MT5 Strategy Tester actually do when you hit Start?
Outside real-ticks mode, the MT5 simulator rebuilds ticks from each bar, takes the spread from history and can fill orders in "ideal" conditions. What does each report assume? The five questions to ask before you believe it.
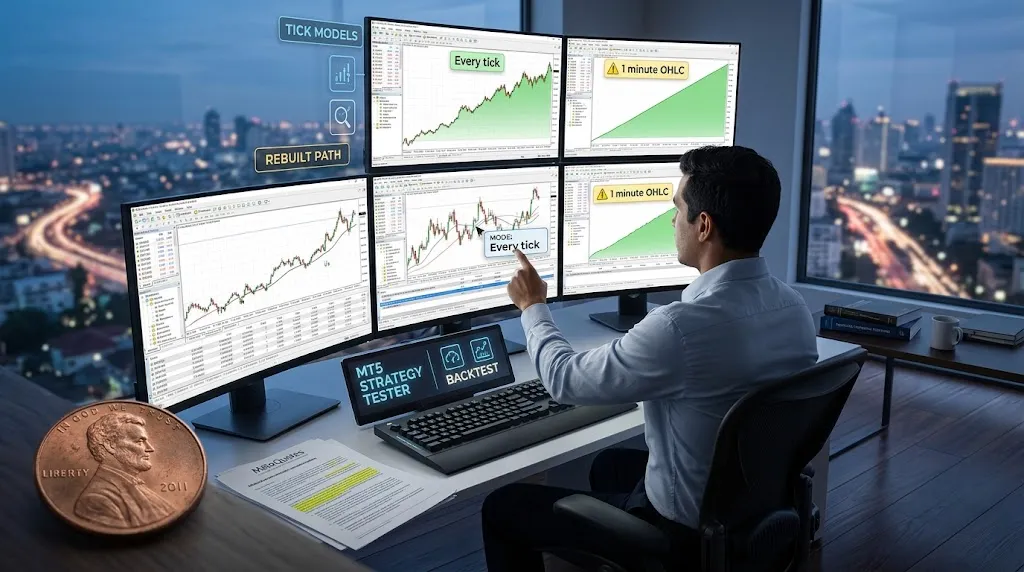
Which tick model did that backtest use, and why does it change the result?
MetaQuotes' own documentation explains how its "1 minute OHLC" mode can manufacture a "Testing Grail". What does the robot see in each mode? The mode worth asking for, depending on the strategy, and a robot published in 2011 that still proves it.
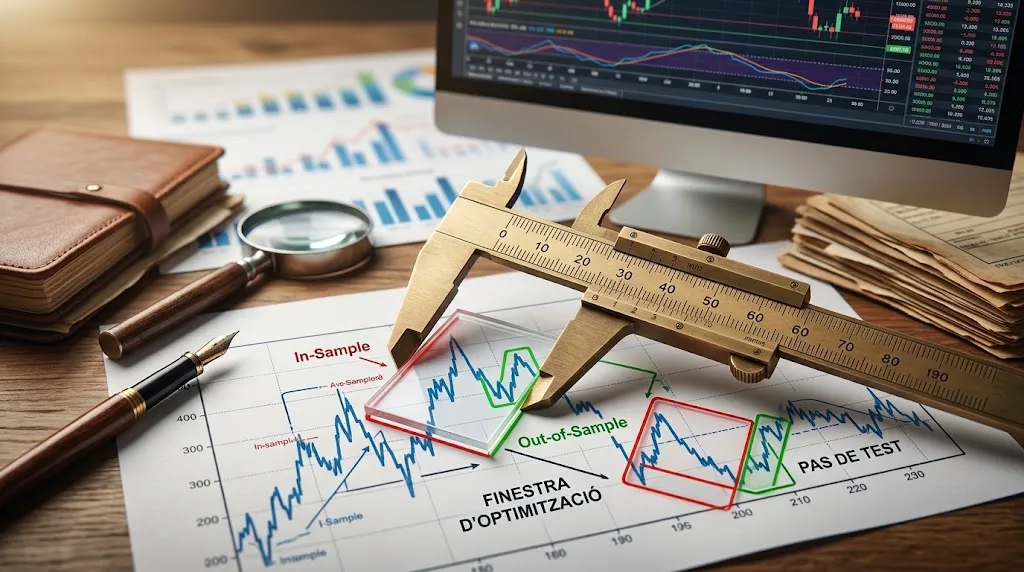
What is walk-forward, and why is it more honest than a single optimisation?
Optimising picks the parameters that did best in the past; walk-forward tests them on data they have not seen, stretch by stretch. What does MT5 ship with? What to look at when it is done, what the method does not fix, and what to ask of a report.
Is a robot from the MQL5 Market worth buying?
The MQL5 Market rules forbid promising profits and passing a backtest off as real trading, and they do not guarantee that any robot makes money. So what does a product page show, and where is the real trading? The questions to ask before paying.
Backtest vs forward test vs walk-forward: three tests, and only one runs in real time
Backtest and walk-forward both run on the past; only a forward test runs on prices that did not exist yet. The three side by side, and the MT5 option that borrows the name.

