CPI vs PPI vs PCE: the inflation number the Fed actually watches
What does each one measure, why is the Fed’s target written on PCE, and which one actually moves the dollar? Three inflation measures, one month, two points apart.
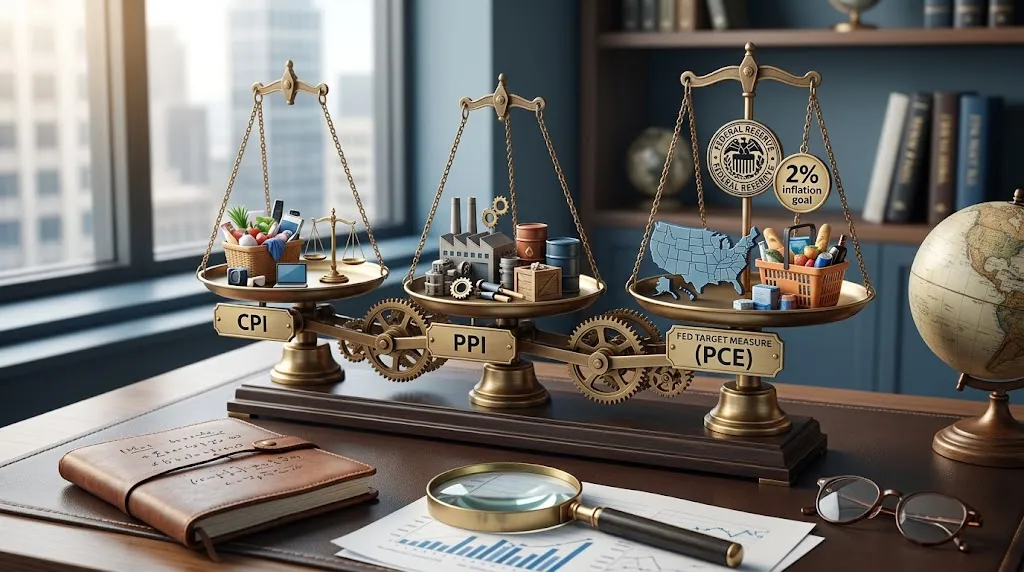
The United States publishes three separate measures of inflation every month, and they rarely tell the same story. In the data for August 2026, producer prices were rising at 5.4% a year while consumer prices rose 3.4% — the same country, the same month, two points apart. Neither of those is the index the Federal Reserve uses to define its 2% goal.
Why are there three inflation numbers for the same month?
Because they answer three different questions, and two different agencies ask them.
| Measure | Published by | Whose prices it tracks |
|---|---|---|
| CPI | Bureau of Labor Statistics | What urban consumers pay |
| PPI | Bureau of Labor Statistics | What domestic producers receive |
| PCE | Bureau of Economic Analysis | What is spent on consumption, including on households' behalf |
The distance between 3.4% and 5.4% is not a contradiction, and neither figure is wrong. They are readings taken at different points of the same chain, by people asking different things.
Once you know which point each one measures, a month where they disagree stops being confusing and starts being informative.
What does each one actually measure?
The Consumer Price Index (CPI) tracks the average change in the prices urban consumers pay for a basket of goods and services. It is the inflation households feel, and it is what most people mean when they say "inflation".
The Producer Price Index (PPI) measures, in the words of the Bureau of Labor Statistics (BLS) that publishes it, "the average change over time in the selling prices received by domestic producers for their output". Its headline is final demand, which combines goods, services and construction.
The PCE price index is defined by the Bureau of Economic Analysis (BEA) as "a measure of the prices that people living in the United States, or those buying on their behalf, pay for goods and services". That last clause is the practical difference with CPI: PCE also counts spending made on households' behalf, so it covers a wider slice of the economy and weights it differently.
All three also come in a core version, which strips out food and energy — the two most volatile components — to show the underlying trend. Calendars list core as its own line, and it is usually the line traders read first. PPI also has a stricter core that leaves out trade services as well, so check which one a report is quoting.
Why does the Fed target PCE instead of CPI?
Because the Fed wrote its goal that way. The 2% target is defined "as measured by the annual change in the price index for personal consumption expenditures" — not the index the public knows, but the one the BEA builds.
That choice has a consequence worth holding on to. CPI is the number that leads the news, and PCE is the yardstick the Fed judges itself against. When the two drift apart, the market has to decide which story the Fed will act on, and the answer is written into the framework the Fed set for itself.
The monthly core PCE readings show how small the decisive decimals are. According to the BEA, core PCE rose 0.3% month on month in May's report, published on 25 June; 0.1% in June's, published on 30 July; and 0.2% in July's, published on 26 August. A monthly 0.2% compounds to roughly 2.4% a year — close enough to target for the argument to be about decimals.
On the headline side, the BEA's July reading, published on 26 August, put prices 3.7% above a year earlier. Still above the goal, and still the yardstick that counts.
Which one moves the dollar?
Mostly, the order in which they arrive.
The three do not land together. In August 2026, July's CPI came out on the 12th, July's PPI on the 13th and July's PCE on the 26th. The order of the first two is not fixed — for August's data, PPI arrived the day before CPI — but PCE closes a month the other two opened weeks earlier.
- CPI usually moves most, because it is the release the public and the press react to, and it reaches the market before PCE has anything to say.
- PPI is read as a hint, not a forecast. A producer facing higher costs can pass them on, absorb them in margin, or wait — so the link to consumer prices is real but not automatic.
- PCE moves least, most of the time, because by the time it arrives much of its content is already public and the forecast has been adjusted to match.
That last point cuts both ways. When PCE does surprise, it carries weight precisely because the market believed it already knew the answer.
And in every case the mechanism is the same: what moves price is the surprise against the forecast, not the level of the number. August's CPI matched its 3.4% forecast exactly; August's PPI came in at 5.4% against the 5.3% the market expected, on the consensus figures InvestingLive published alongside each release.
Read the core lines instead and the ranking inverts. Core CPI rose 0.3% month on month against the 0.2% expected, while PPI's underlying measure eased to 0.3%. Which of the two looked hotter depended entirely on which line you read — this post's argument, inside a single month.
From there the chain is the usual one: more inflation pressure means more reason for the Fed to keep policy tight, which is read as hawkish and tends to support the dollar. Less pressure does the opposite.
How should you read a month where they disagree?
Start by asking which one disagreed, and in which direction.
What carries information is the gap moving, not the gap existing: the two track different baskets, so some distance between them is normal and permanent. Producer prices pulling away from consumer prices point to cost pressure that has not reached the shopper yet. It may never arrive in full — margins absorb some of it — but it is a reason to expect the next CPI to be watched more closely than usual.
The reverse case matters more for rate decisions. Consumer prices running hot while producer prices cool means the pressure is not coming from producer costs, so it sits in the parts of consumer inflation that PPI does not track — and those are usually the slowest to come down.
And when CPI and PCE part company, remember which of the two the 2% goal is written on.
What this post does not give you
It does not tell you how much of a PPI move will reach consumer prices, or when. That pass-through changes from one cycle to the next and nobody publishes it in advance.
It does not let you predict PCE from CPI. The two cover different baskets with different weights, which is exactly why the Fed distinguishes them.
And it is not a trading rule. Each of these releases is one input among several on the same day, and the reaction depends on what the market had already priced in.
The takeaway
CPI is the inflation the public feels, PPI is the pressure building behind it, and PCE is the one the Fed measures its own 2% goal against. Read them as one story told from three places, watch the core line in each, and judge every print against its forecast rather than against your own sense of what is expensive.