The welcome bonus is charged back to you in spread
A 100% bonus cannot be withdrawn until you trade a set volume, and that volume is paid in spread. Break-even sits at 62.5 EUR/USD lots. What did ESMA write when it banned them in 2018, and why is the real cost the condition rather than the balance?
A 100% deposit bonus sounds like free money. You put in $500 and the platform shows $1,000.
That second balance is not yours yet, and the route to making it yours is written into the bonus terms. This article is about that route, which is walked by paying spread on every trade.
In the European Union and the United Kingdom the product no longer exists for retail clients: it has been banned since 2018. If someone is offering you one today, that tells you something too.
How is a bonus built?
The shape is nearly always the same. The bonus shows up in the balance but cannot be withdrawn until a volume requirement is met: trading a set number of lots, sometimes inside a limited window.
The European regulator described that mechanism as it banned it. The European Securities and Markets Authority, ESMA, sets it out in its decision&from=EN), in recital 49:
"Furthermore, such trading benefits to open CFD trading accounts often require clients to pay funds to the provider and conduct a specified number of trades…"
And recital 48 explains what worried it:
"Bonuses and other trading benefits can act as a distraction from the high-risk nature of the product. They are typically targeted to attract retail clients and incentivise trading."
Look at the last verb: incentivise trading. Not reward accuracy, not offset a commission. Incentivise volume.
The arithmetic, which is the uncomfortable part
Every lot you trade leaves a toll behind. We measured ours in the spread article: on EUR/USD, a standard lot carries a pip value of about $10, so a 0.8-pip spread costs roughly $8 every time you open and close a position.
With that number you can answer the only question that matters: how much volume does it take for the toll to equal the bonus?
| Lots required | Spread paid at 0.8 pips | Against a $500 bonus |
|---|---|---|
| 25 | $200 | The bonus is still ahead |
| 50 | $400 | Nearly level |
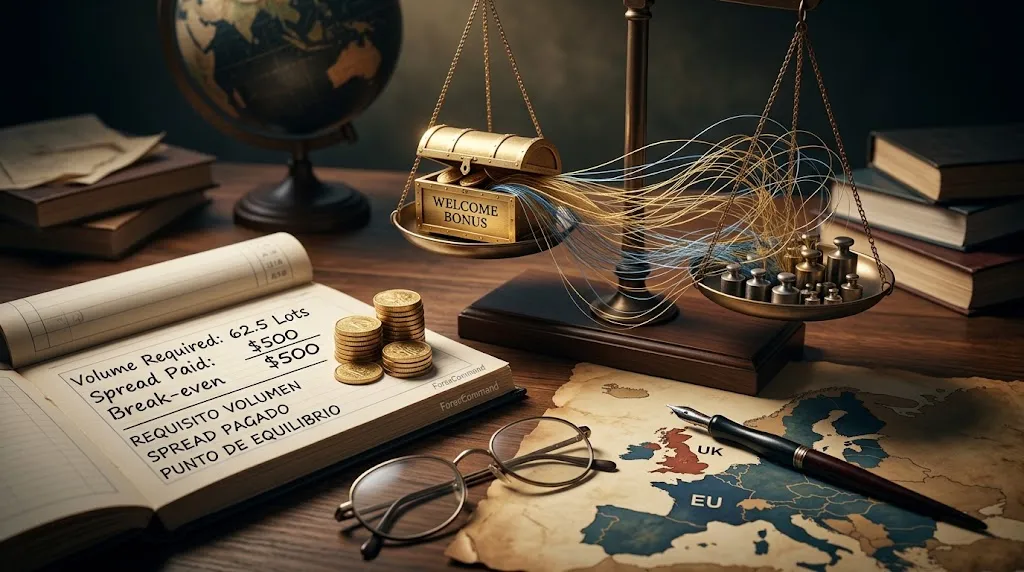
| 62.5 | $500 | Exact break-even |
| 125 | $1,000 | Twice what they gave you |
| 250 | $2,000 | Four times |
Sixty-two and a half lots. That is the threshold to read any bonus condition against: below it the bonus pays, above it you did.
Two things make the sum worse and are not in the table. The first is that the spread is not always 0.8: on exotic pairs, overnight, or around a data release it is several times wider. The second is that required volume is rarely traded slowly — the deadline pushes you to trade more and worse, which is exactly what ESMA described.
The trap that is not about money
There is a second effect, subtler than the arithmetic.
A volume requirement changes what you do with the chart. A trading plan decides when not to trade; a lot requirement decides that you trade anyway. Those are incompatible instructions, and the one with a deadline usually wins.
From there the chain is familiar: more trades than your edge justifies, bigger sizes to finish sooner, and a risk of ruin that climbs with each one. The bonus does not have to make you lose in order to cost you money: changing your frequency is enough.
It is worth saying plainly, because this gets confused: the problem is not the extra balance, it is the condition that releases it.
A bonus is not leverage, even though it looks like it
Both put a number on screen that is bigger than your money, and the resemblance ends there.
Leverage expands the position size you can open against your margin. It does not give you capital: it lets you control more notional, with losses magnified in the same proportion.
A bonus really is balance added to the account, but conditioned — and in many contracts only the profit it generates can be withdrawn, never the bonus itself. Two different mechanisms; do not run them together on the same intuition.
What the regulators decided
This is not an editorial opinion, it is a written rule. ESMA's decision has only four articles, and the ban sits in Article 2, which lists the conditions without which a CFD cannot be sold to a retail client. Its point (d):
"the CFD provider does not directly or indirectly provide the retail client with a payment, monetary or excluded non-monetary benefit in relation to the marketing, distribution or sale of a CFD, other than the realised profits on any CFD provided"
The drafting is tighter than it looks. The only thing the rule lets them hand you is what you earned by trading. Anything else added to your balance, under whatever name, falls inside the ban.
| Scope | |
|---|---|
| ESMA, European Union | Monetary and non-monetary benefits to retail clients banned, from 2018 |
| FCA, United Kingdom | Permanent from July 2019: firms must stop offering cash or other inducements |
The UK's Financial Conduct Authority folded the inducement ban into the same package that set maximum leverage and negative balance protection, and estimated the combined saving to UK consumers at between £267m and £451m a year.
The practical consequence is direct. A deposit bonus offered today to a European or British resident cannot be coming from an entity regulated there. It will come from a group company licensed in another jurisdiction, and that is information about who you are signing with, not an administrative detail: why a regulated broker matters develops it, and is my money safe explains what it changes if something goes wrong.
What this article does not tell you
It does not say every bonus is a fraud. A bonus with a low volume requirement and no deadline can come out in your favour; the table above exists so you can check that rather than believe it.
It does not say that offering bonuses is illegal. Outside the European Union and the United Kingdom they are perfectly legal, and serious jurisdictions permit them.
It does not rate specific brokers or compare promotions, and it does not claim nobody ever withdraws a bonus. People do; what is under discussion here is what it cost to get there.
What it gives you is the calculation the promotion leaves out: divide the bonus by the cost per lot on your pair, and see whether the number lands above or below the volume they are asking you to trade.