Core PCE undershoots at 0.2%, yet yields and the dollar end higher
Softer US core PCE trimmed bets on an October Fed hike and briefly lifted the euro, but yields and the dollar ended Wednesday higher; the Australian dollar lost 0.57%.
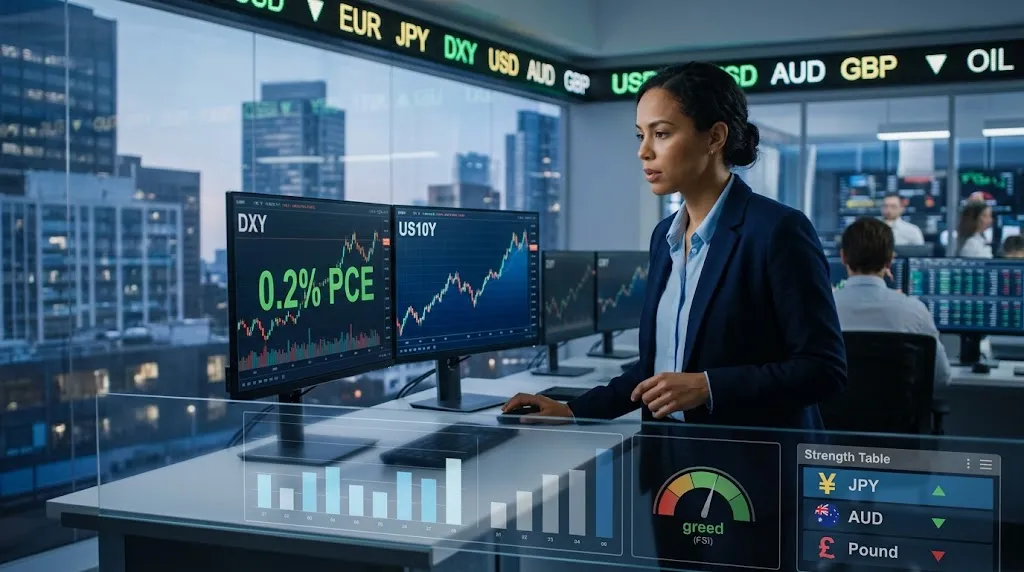
Softer US core inflation trimmed bets on an October Fed hike on Wednesday and briefly lifted the euro, but by the close Treasury yields were higher and the dollar had gained against most majors, according to investingLive. The Australian dollar lost 0.57%, and the yen led our strength table.
What the data showed
- US core PCE prices rose 0.2% on the month in August, below the 0.3% forecast. ADP employment rose by 90,000 against 73,000 expected, and the Bureau of Economic Analysis's final second-quarter GDP estimate put growth at 2.2% annualised and revised its price measures down, with the second-quarter PCE price index at a 5.0% annualised rate.
- Australia's CPI rose 4% on the year, up from 3.5% and just under the 4.1% forecast; the trimmed mean rose 0.2% on the month against 0.3%.
- European inflation ran hot again after Spain's figure on Tuesday: Italy's preliminary September CPI came in at 4.2% on the year against 3.8% expected, and Germany's at 3.3% against 3.1%, according to investingLive.
The dollar, yields and the Fed
- The softer PCE led traders to trim bets on another Fed hike in October, FXStreet reported, and EUR/USD was modestly higher, around 1.1363, in the New York morning. In Asia it had traded near 1.1330, close to its lowest since May 2025, according to FXStreet.
- The lift did not last. By the end of the session Treasury yields were higher and the dollar had strengthened against most majors, investingLive's Americas wrap said, and FXStreet had the euro on course to lose more than 2% in September. Fed Governor Lisa Cook said inflation had stayed too high for too long.
The Australian dollar, yen and commodities
- The Australian dollar lost 0.57% against the US dollar, according to FXStreet, which had it below 0.70 after the close and said the dovish tilt from RBA Governor Michele Bullock outweighed the softer US data.
- USD/JPY edged up 0.08% to 157.42 after the close, with its 50-day moving average capping it near 158.00, according to FXStreet. That leaves it well short of last Thursday's 159.02, the level our weekly wrap is watching.
- Oil turned higher after Tuesday's slide. FXStreet had WTI above $88.00 in early European trading after President Trump denied Iran sanctions relief, and cited Axios as reporting that Qatar's mediation between Washington and Tehran had made little progress.
- Gold extended its rebound from an eight-week low, trading near $4,180 in Asia according to FXStreet, which said buyers were waiting for it to hold above $4,200; investingLive's European wrap said the recovery continued. Silver came under pressure near $60, according to FXStreet.
Market gauges and what's next
Our proprietary metrics at the close of the session:
- Top of our strength table: the yen, on top for 298 of the session's 1,440 minutes (21%). The Australian dollar was second on 238, on the day it lost 0.57%: the table counts minutes in first place, not how far a currency moved.
- Bottom: the pound, in last place for 22% of the minutes and on top for just 55.
- The dollar: fifth, on top for 166 minutes, after finishing narrowly third on Tuesday.
Still ahead today: Bank of England Governor Bailey speaks at 08:00 UTC. In the US, jobless claims (forecast 201,000) and the ISM manufacturing survey (forecast 54.8) are due at 12:30 and 14:00 UTC, and ECB President Lagarde and FOMC member Waller are also scheduled to speak.