What was the Nixon shock?
For five days the dollar bought 357 yen to the second decimal. What was the Nixon shock, and why does every floating exchange rate start there?
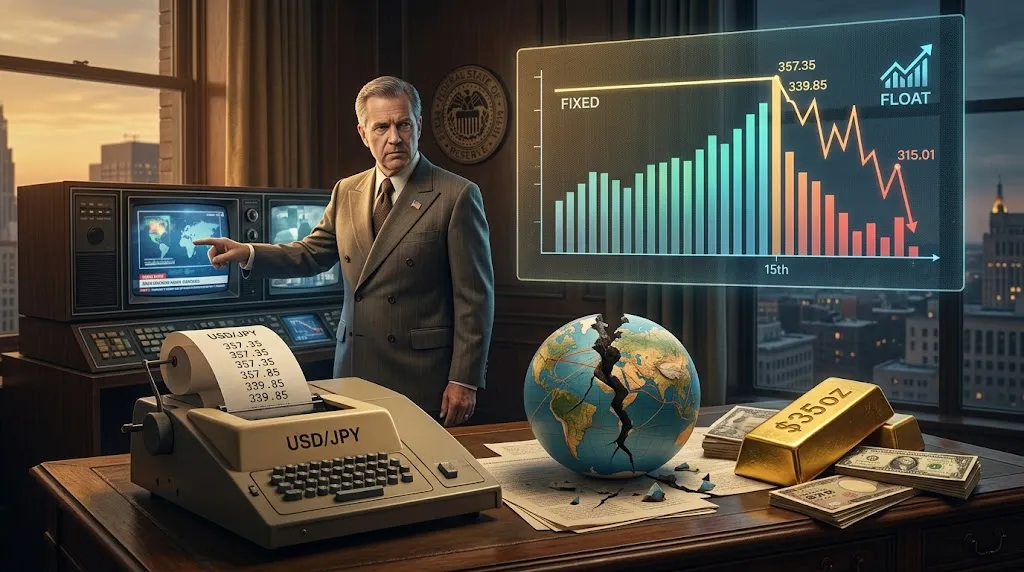
For five straight days in August 1971 the dollar bought 357 yen, to the second decimal. Then a president spoke on a Sunday evening, and the number never sat still again.
What was the system before it?
Under the Bretton Woods arrangement, agreed in 1944, other currencies were fixed against the dollar and the dollar was convertible into gold at $35 an ounce. A foreign government holding dollars could, in principle, present them to the United States and receive metal.
Exchange rates were therefore not a market. They were an administrative number, defended by central banks and changed only by formal decision.
The daily record shows exactly how rigid that was. In the week before the announcement, the dollar closed at 357.35, 357.39, 357.35, 357.40 and 357.35 yen. Five sessions, a total range of five hundredths of a yen.
What did Nixon actually announce?
On Sunday 15 August 1971, President Richard Nixon told a television audience that the United States was suspending the convertibility of the dollar into gold. The commitment at the centre of the system was withdrawn, and with it the reason any of the fixed rates had to hold.
Japan kept its market shut. When the quote resumed on 31 August the dollar was worth 339.85 yen — 4.9% lower than the level it had held for years.
How far did it actually go?
| Date | USD/JPY | Change from the peg |
|---|---|---|
| 13 Aug 1971 (last pegged session) | 357.35 | — |
| 31 Aug 1971 (quote resumes) | 339.85 | −4.9% |
| 31 Dec 1971 | 315.01 | −11.8% |
| 31 Dec 1973 | 280.27 | −21.6% |
An attempt to rebuild fixed rates at new levels — the Smithsonian Agreement of December 1971 — lasted barely a year. By 1973 the major currencies were floating, and they have floated ever since.
Why does a 1971 broadcast still matter to a trader?
Because it is the reason there is anything to trade. Every chart, every spread, every intervention story exists only because rates stopped being set and started being discovered.
It is also why the dollar index begins where it does: the benchmark starts in 1973, at 100, because that is when there was finally something to measure.
What can a retail trader take from it?
- A fixed rate is a promise, not a law of nature. It holds while someone is willing to pay for it, and the payment is finite.
- The break is not gradual. Years of a five-hundredth range, then a single announcement and no way back.
- Silence in the data is not calm. That flat line was a policy, and the flatness was the warning rather than the comfort.
- The dollar's haven role outlived the gold that backed it. It kept the job after losing the guarantee, which says the role was never really about the metal.
Exchange rates are daily noon figures from FRED series DEXJPUS (Federal Reserve Bank of St. Louis). The announcement of 15 August 1971 and the Smithsonian Agreement of December 1971 are matters of public record.