ECN vs STP vs market maker: who is on the other side of your trade?
Three labels for what a broker does with your order. Which one is yours, and why does the licence say more than the account page?
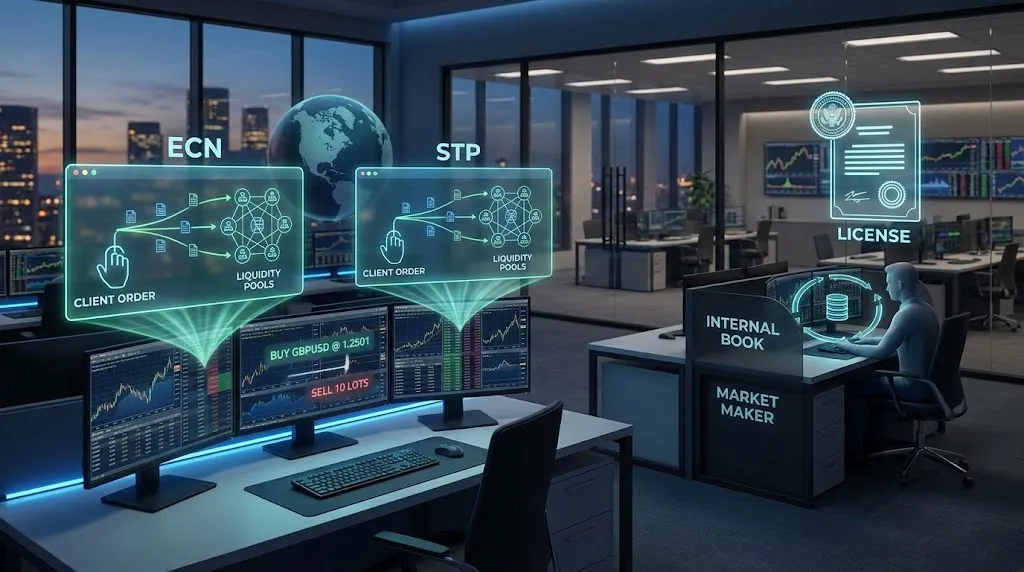
ECN (electronic communication network), STP (straight-through processing) and market maker are three answers to one question: what the broker does with your order. A market maker keeps the risk on its own book, an STP broker passes it to a liquidity provider, and an ECN broker routes the order to a network where several providers quote. None of the three labels is a licence category: what binds the broker is the list of services on its licence, and that list is public.
That is why the label on the account page is the weakest evidence you have. The rest of this article is about the stronger ones.
Three labels, one question
| Where the risk ends up | How the broker earns | What you usually see | |
|---|---|---|---|
| Market maker | With the broker, on its own book | The spread, and your result if it keeps the risk | A spread with everything built in |
| STP | With a liquidity provider behind the broker | Usually a markup added to the provider's price | A spread with the markup inside |
| ECN | With the providers quoting on the network | Usually a commission per lot | A near-raw spread plus a commission |
In a contract for difference (CFD) the broker is still the one that signs the contract with you in all three cases; the labels describe what happens behind it. The last column is the part you can check on a price screen, and also the part that proves least, because a broker can build any of those pricing models whatever it does with the risk.
Market maker: the broker is the other side
The closest legal term is in MiFID II (the Markets in Financial Instruments Directive), the European Union (EU) law under which investment firms are licensed. Its Article 4(1)(7) defines a market maker as "a person who holds himself out on the financial markets on a continuous basis as being willing to deal on own account by buying and selling financial instruments against that person's proprietary capital at prices defined by that person."
Read the last four words: the price is the firm's own. The service underneath is dealing on own account, which Article 4(1)(6) defines as "trading against proprietary capital". In a CFD that is simply how the product works, and as we explained in your CFD broker is the counterparty, the European Securities and Markets Authority (ESMA) did not flag being the counterparty as the problem. In its 2018 decision it flagged the conflict of interest of counterparties that do not hedge, because they "benefit directly from client losses".
A market maker can hedge part of its book and keep the rest. From the outside you cannot tell which part your trade landed in.
This market maker has nothing to do with the Market Maker Model of Smart Money Concepts. They share a name and nothing else.
STP: passed on, but to whom?
Straight-through processing is a back-office term: an order that goes from one system to the next with no human in between. In a broker's marketing it means that your trade is offset with a liquidity provider and the broker does not keep the risk.
The directive has a precise term for the cleanest version of that. Article 4(1)(38) defines matched principal trading as a transaction where the firm "interposes itself between the buyer and the seller to the transaction in such a way that it is never exposed to market risk throughout the execution of the transaction, with both sides executed simultaneously, and where the transaction is concluded at a price where the facilitator makes no profit or loss, other than a previously disclosed commission, fee or charge for the transaction".
Read the second half. A broker that earns a markup it has not disclosed in advance is not doing what that definition describes, whatever its account page says. Recital 24 adds that a firm matching orders "from different clients" this way "should be regarded as acting as principal", which is the point we made in your CFD broker is the counterparty: the broker is the party you sign with, and STP describes where the risk goes after that.
ECN: defined in law, just not in forex
The term does exist in law, in American stock market rules. The Securities and Exchange Commission's Regulation NMS (National Market System), in the Code of Federal Regulations at 17 CFR 242.600(b)(36), defines an "electronic communications network", for the purposes of one of its rules, as "any electronic system that widely disseminates to third parties orders entered therein by an exchange market maker or OTC market maker, and permits such orders to be executed against in whole or in part".
The same definition then excludes "any system operated by, or on behalf of, an OTC market maker or exchange market maker that executes customer orders primarily against the account of such market maker as principal, other than riskless principal". Where the law does define the term, a dealer filling orders mainly against its own book is exactly what an ECN is not.
The operative idea is that other people's orders are visible and can be hit. Forex has no such central venue. As we explain in our piece on order books and depth of market, each broker or network sees its own providers and nothing more.
So an "ECN account" is a claim about how your order is priced and routed. It is not a claim you can check against a legal definition.
What the licence says instead
MiFID II does not use the abbreviations ECN or STP anywhere. What it uses is a list of investment services in Annex I, Section A, and three of them are the ones this question turns on:
| Service in Annex I | What it covers | Which label claims it |
|---|---|---|
| (1) Reception and transmission of orders | Passing your order to another firm | STP, in its strictest sense |
| (2) Execution of orders on behalf of clients | Concluding the trade for you | STP and ECN |
| (3) Dealing on own account | "Trading against proprietary capital" | Market maker, and back-to-back matching between clients under recital 24 |
The last column is ours: the directive does not map any label to any service. Article 6(1) requires the licence to specify "the investment services or activities which the investment firm is authorised to provide". Article 5(3) requires every member state to keep a public register of investment firms that "shall contain information on the services or activities for which the investment firm is authorised".
An actual network where many participants' orders meet is a different service again: a multilateral trading facility (MTF), a system that "brings together multiple third-party buying and selling interests", or an organised trading facility (OTF). Operating them is service (8) or (9) on the same list.
How to check your own broker
- The register, not the website. Find the entity that signs your contract, look it up on its regulator's public register, and read the services listed. If "dealing on own account" is not there, the firm is not authorised to deal with you as principal. If it is, it may be, for the instruments its licence covers: CFDs are item (9) in Section C of the same annex.
- The execution policy. Article 27 requires EU firms that execute client orders to have an order execution policy that lists "the different venues where the investment firm executes its client orders", and to give clients information on it. Read who those venues are.
- The percentage of losing accounts. EU CFD providers must publish it, as we covered in your CFD broker is the counterparty. It does not tell you the model, but it tells you what the model produced.
- The cost, all in. An ECN-style account moves the cost from the spread to the commission, as what a trade really costs shows. Compare the total, not the headline.
- The execution mode. MetaTrader 5 (MT5) shows it per symbol, and it decides whether you see requotes or silent slippage, as in slippage vs requote vs gap. It tells you how your order is filled. It does not tell you who keeps the risk.
What this does not tell you
- Which broker to use. We have not checked any broker's register, execution policy or fills. Our broker checklist gives the order in which to rule them out.
- Much outside the EU. The services and the register come from MiFID II. The UK, Australia and the US each license brokers under their own rules. In the US, a firm that is, or offers to be, the counterparty to a retail forex transaction is, with some exceptions set out in the law, a retail foreign exchange dealer under the Commodity Futures Trading Commission (CFTC) rules in 17 CFR Part 5, and must register. And the only legal definition of an ECN we found belongs to US equity markets, not to forex.
- Whether a market maker is worse. For an authorised EU firm, keeping the risk is legal, disclosed and supervised. A broker that hedges everything still charges you on every trade.
- How much of a book is hedged. A licence says what a firm may do, not what it does with each trade on a given day.
The takeaway
ECN, STP and market maker describe a business model in sales language. The licence describes it in legal language, and only one of the two can be looked up. Before asking a broker what kind of broker it is, ask the register what it is allowed to be.